
Economic Snapshot – August 2026
USA and Emerging Markets produced positive returns in August, and this was due to strong earnings results, and best amongst the tech sector. In Australia, small companies bounced back with a strong 5% return in August, and this was also due to stronger than expected earnings announcements.
This August economic snapshot article is prepared by Michael Furey, Principal of Delta Research & Advisory, on behalf of the HPartners Group.
Summary
- Higher energy prices continue, leading to a higher for longer view of cash interest rates, and slightly higher bond yields. This has increased the expected returns for boring bonds which are expected to return over 5% over the next five to ten years, which should appeal to many investors that are concerned by sharemarket valuations. This appeal is a forward expectation and despite weak returns bonds have produced over the last 5 years and in August.
- USA and Emerging Markets produced positive returns in August, and this was due to strong earnings results, and best amongst the tech sector. In Australia, small companies bounced back with a strong 5% return in August, and this was also due to stronger than expected earnings announcements.
- Economically, inflation has persisted at higher levels than desired at over 3% in USA, Australia, and Europe. Unemployment levels remain relatively low although leading indicators suggest weakness in Australia and USA. Expectations are that unemployment will slowly increase over the next 12 months.
- Our core investment message remains due to persistent downside risks from high sharemarket valuations in USA and the energy crisis. This means disciplined risk management rather than aggressive position changes. Shares continue to offer an attractive risk premium in specific markets, as do conservative bonds, but returns may be challenged from occasional short-term volatility. Avoiding panic (selling) decisions continues to be a crucial investment issue today for long-term investors.
Chart 1
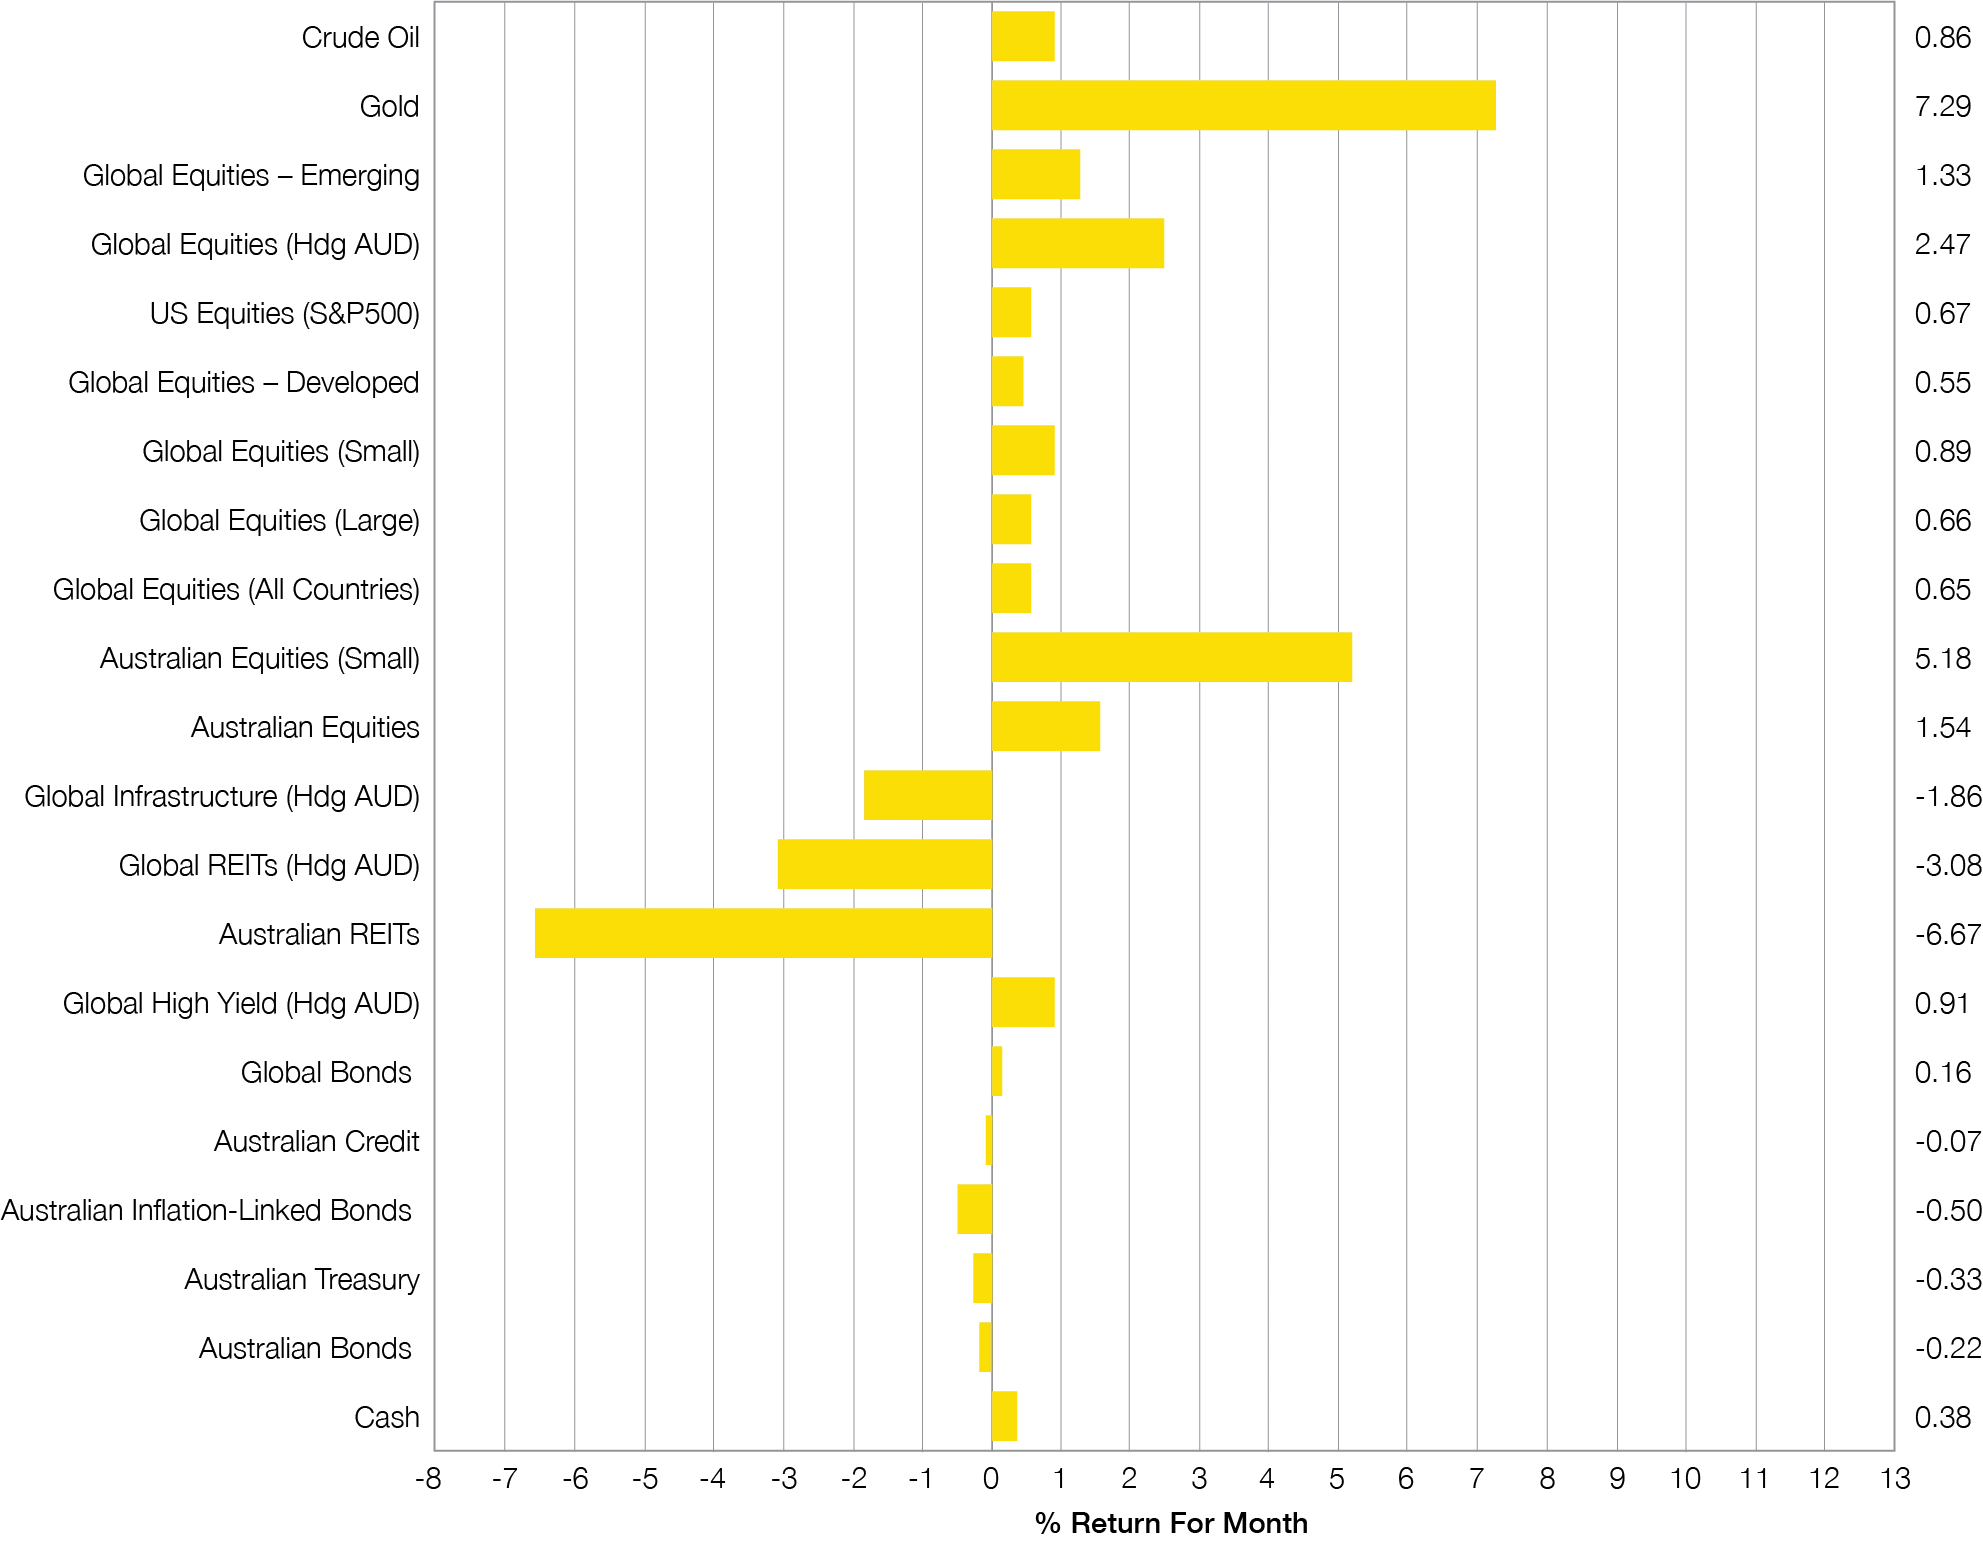
High bond yields … weaker real asset returns
What Happened Last Month?
Markets & Economy
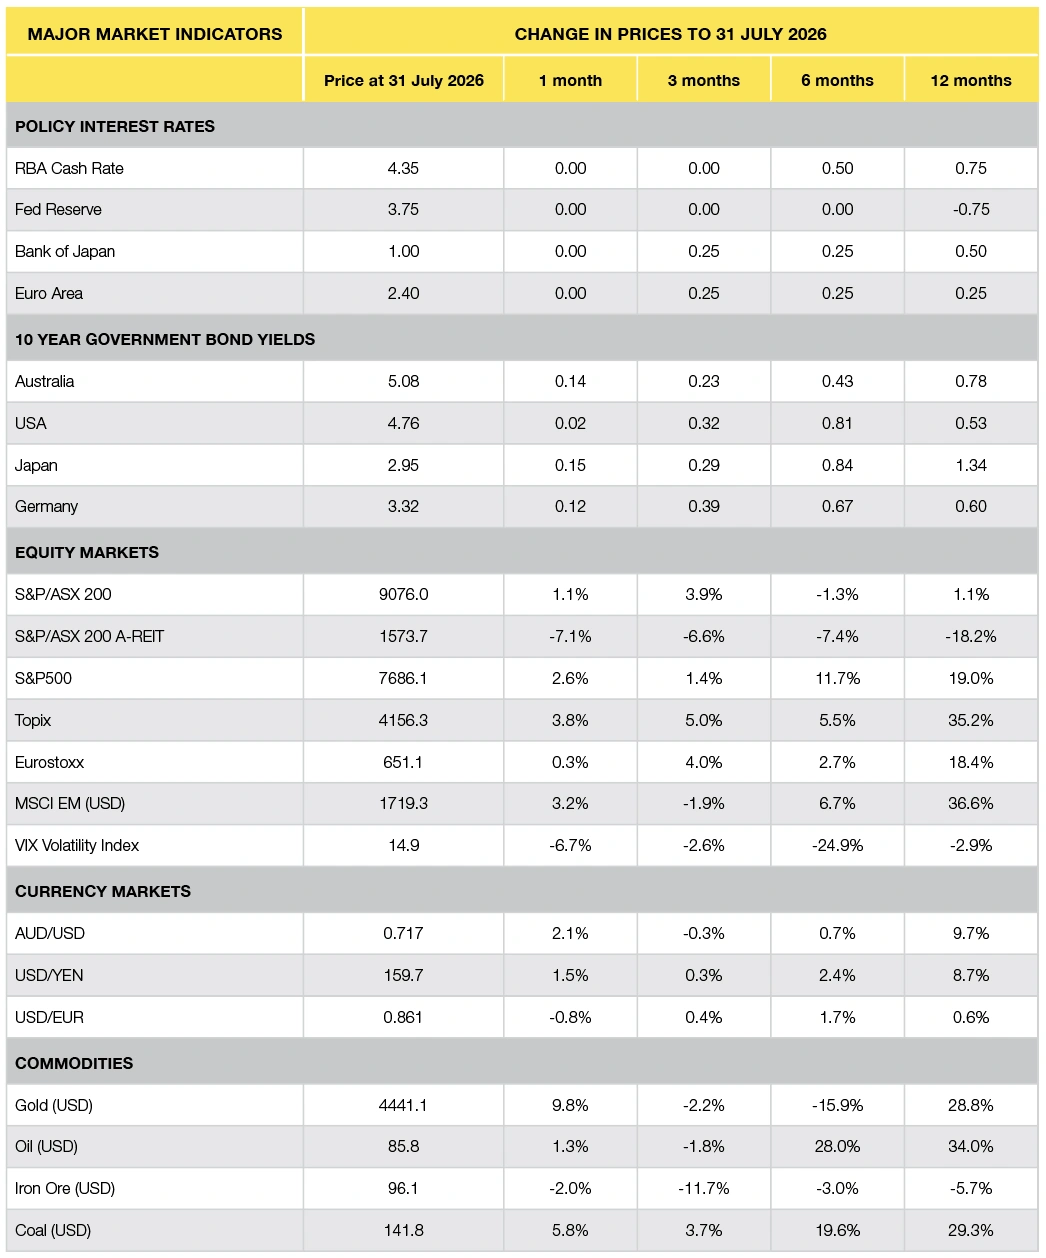
- The dominant discussion during August centred on higher inflation from the USA Administration’s continued war with Iran, keeping energy prices high, plus their inflation-inducing tariffs resulting in the higher for longer cash rates and ultimately higher bond yields. In the USA, 30-year bond yields increased substantially, and this is most relevant to the cost of housing as most USA mortgages are fixed for 30 years. However, 10-year bonds ended only 2bps higher at the end of August compared to the end of July.
- Higher bond yields negatively impacted the longer duration Real Assets, and the worst performing asset classes in August came from Australian REITs (-6.7%), Global REITs (-3.1%), and Global Infrastructure (-1.9%).
- Whilst higher bond yields resulted in weak returns around the world for bonds and real assets, sharemarkets were up a little and helped by generally good earnings announcements. In Australia, smaller companies benefited most and were up over 5%, whilst Emerging Markets, Global Developed Markets and broad Australian shares were up between 1.3% and 2.5%.
- Economic results around the world were relatively steady with most inflation results continuing above central bank targets at over 3%. Unemployment is steady and there were few announcements around economic growth.
Outlook
- The continuation of higher inflation in Australia has resulted in a strong likelihood of one more rate increase before the year is out … this is a change from last month where this likelihood was priced by markets as being low.
- Bond yields around the world have increased and consolidate views that expected returns for fixed interest is to be around 5+%pa over the next 5-10 years. This continues to be appealing in the face of expensive sharemarkets.
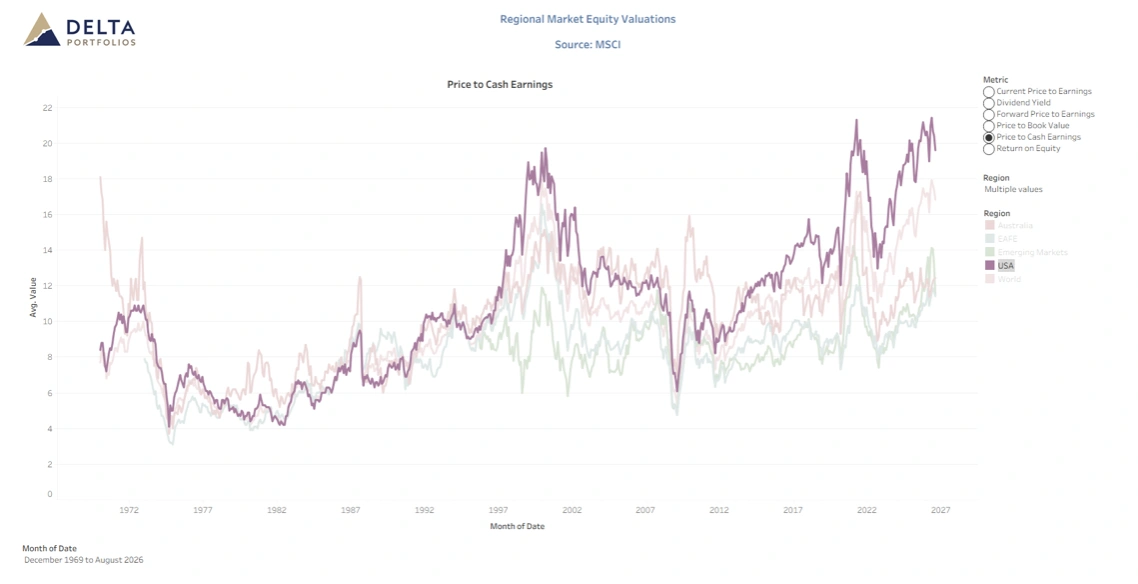
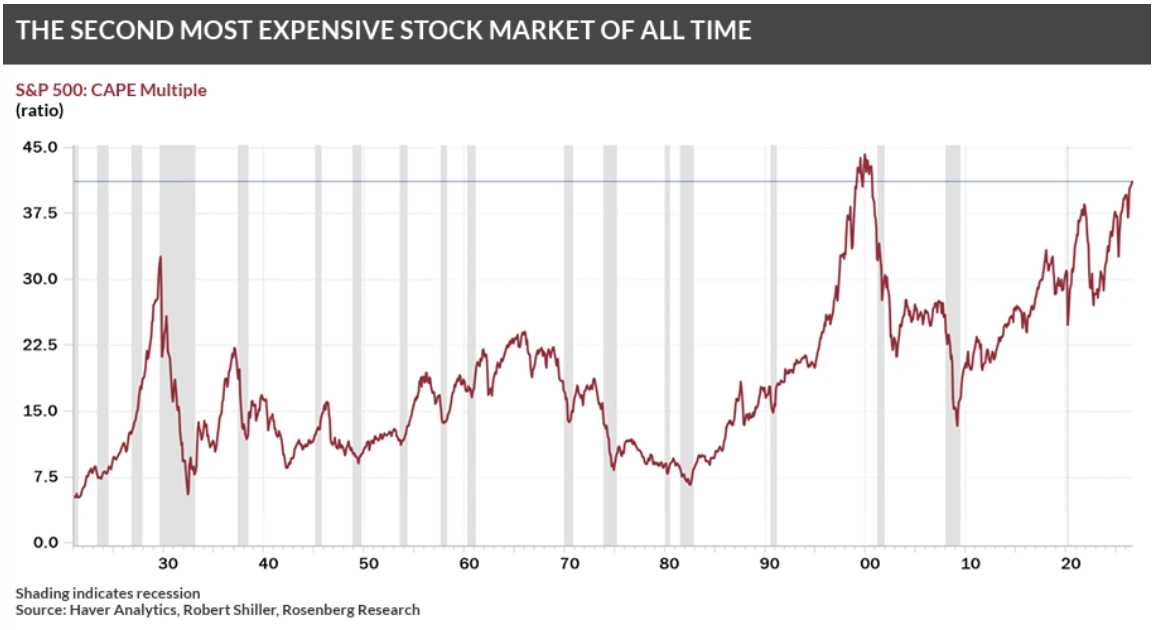
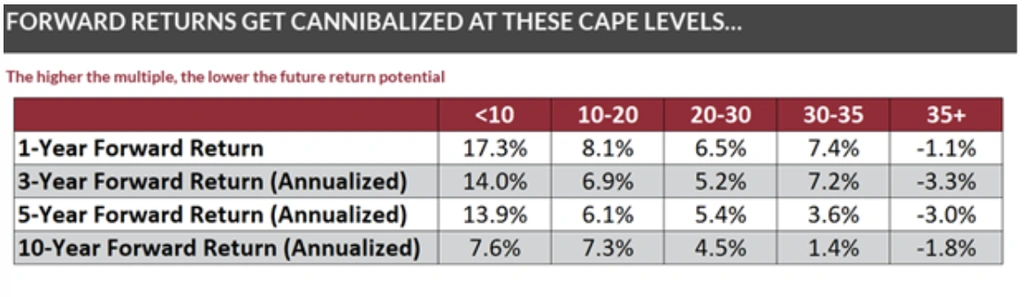
- US markets continue to be near record high valuations and are generally forecast to be weaker than non-USA sharemarkets over the next 10 years. As previously mentioned, this doesn’t mean any imminent crash is likely, but caution should always be appropriate with expensive markets.
- Our core message remains as we continue to believe portfolios should be underweight USA shares and high yield (junk) bonds due to these near record high valuations. By comparison, defensive Cash and bond portfolios both global and in Australia, are providing strong relative expected returns at over 5%pa.
- Our current beliefs are that new investors should dollar cost average into sharemarkets and long-term investors should stay invested for the long-term but should expect and get used to higher volatility.
- Diversification continues to be essential. Maintaining a balance between domestic and global exposures remains a prudent approach as 2026 unfolds. Rebalancing as pricing opportunities arise also continues to be appropriate for established portfolios.
Major Market Indicators
Source: Morningstar, Trading Economics, Reserve Bank of Australia
31 August Market Valuations Since 1969 – Price to Cash Earnings. Improvement in USA but still high
Published:
Share
Resources
A wealth of knowledge
Latest News
-
Discover How to Hand Over a Business to Family
 September 15, 2026
-
Economic Snapshot – August 2026
September 15, 2026
-
Trust vs Company: The Big Structure Decision
September 7, 2026
-
The Centrelink Pension Increase: 3 Things to Check
September 7, 2026
-
Credit Card Surcharge Ban 2026: Rewards Points Are Shrinking
September 1, 2026
-
Easy First Home Buyer Financial Advice in Australia
September 1, 2026

Tools & Guides
Useful tools & guides to get you started
 Find out more

Video Guides
Useful videos to get you started
Find out more

Financial Calculators
See what impact little changes can have
Find out more